Buying a property is likely to be one of the largest financial commitments you will ever make. However, when budgets are stretched by deposits, legal fees, mortgage costs and Stamp Duty, buyers can sometimes be tempted to reduce their pre-purchase costs by foregoing a detailed property survey.
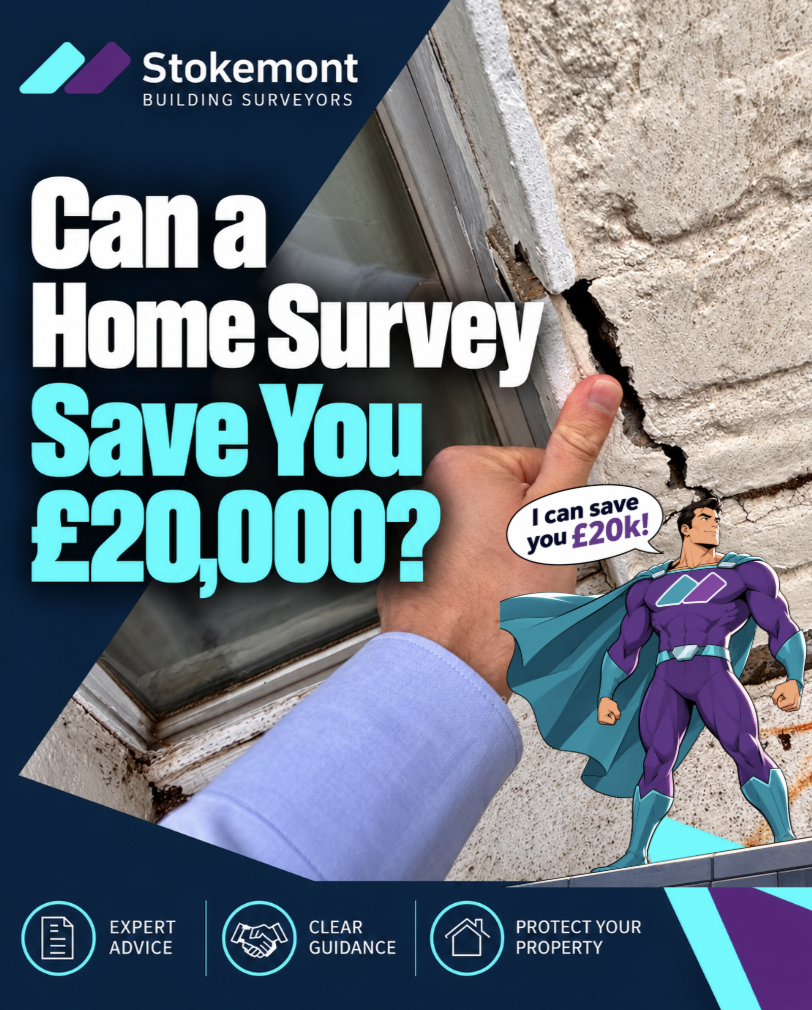
With the average domestic subsidence claim now reaching around £20,000, this can prove to be a very costly false economy.
Subsidence can be one of the more serious defects affecting a property. It occurs when the ground beneath a building moves downwards, potentially resulting in movement to the foundations and structure above.
There can be a number of causes.
Clay soils may shrink during prolonged dry weather, nearby trees and vegetation can draw moisture from the ground, leaking drainage can affect surrounding soils and historic alterations or foundation issues can also contribute to movement.
The difficulty for a homebuyer is that the early warning signs are not always obvious.
Cracking is extremely common in buildings and does not automatically mean that a property is suffering from subsidence. Many cracks are associated with normal settlement, thermal movement, shrinkage or relatively minor decorative issues.
The important point is understanding when cracking may indicate something more serious.
Warning signs can include cracking that appears suddenly, diagonal cracking, wider or progressive cracks, corresponding cracking internally and externally, or doors and windows unexpectedly becoming difficult to open and close.
These are exactly the types of issues an experienced Building Surveyor will be considering during a pre-purchase inspection.
Insurance Does Not Remove the Financial Risk
It is also important not to assume that buildings insurance makes a subsidence problem financially insignificant.
Home insurance policies usually include an excess, meaning the policyholder has to contribute towards the cost of a claim.
Subsidence claims commonly carry a significantly higher excess than an ordinary buildings insurance claim, with an excess of around £1,000 being common.
For properties with a history of subsidence, the excess can be higher still.
There can also be consequences beyond the immediate cost of the claim.
A history of subsidence can affect future insurance premiums and availability, while also becoming an issue when the property is eventually sold. In some cases, insurers may require monitoring and investigation before accepting that movement has stabilised, which can make the process lengthy as well as expensive.
This is why identifying potential issues before exchange of contracts is so important.
A Survey Gives You the Opportunity to Act Before You Own the Problem
A pre-purchase survey is not simply about producing a list of defects.
Its real value lies in giving the purchaser a clear understanding of the condition of the property before they become legally committed to buying it.
At Stokemont, our RICS Level 2 HomeBuyer Reports are suitable for many flats, conventional properties where the buyer requires a clear assessment of condition and identification of significant defects.
For houses, older, altered, unusual or more complex properties, a RICS Level 3 Full Building Survey provides a significantly more detailed inspection and report.
Both surveys allows the Surveyor to consider the property in greater detail, identify defects, comment on likely causes and provide practical advice on the severity of the issues and likely remedial requirements.
Structural movement and potential subsidence are among the key issues our Surveyors consider during these inspections.
The Survey Can Change the Financial Decision
If a survey identifies significant cracking or evidence suggesting structural movement, that does not automatically mean that the purchase should be abandoned.
It does, however, put the purchaser in a far stronger position.
Further structural investigation may be recommended. Historic reports and repair documentation can be requested. Insurance history can be reviewed. Drainage investigations may be appropriate. Repair costs can be established.
Most importantly, the purchaser can take those findings into account before committing to the agreed purchase price.
That can create an opportunity to renegotiate.
If the issue is serious enough, it may also give the buyer the information they need to reconsider the purchase altogether.
That is where the cost of a survey can quickly become insignificant when compared with the financial exposure it may help a buyer avoid.
If the average subsidence claim is around £20,000, with a potential insurance excess of around £1,000, spending a comparatively modest amount on an appropriate pre-purchase survey can represent extremely good value.
A survey may identify an issue before exchange, enabling the buyer to investigate, negotiate or withdraw before becoming responsible for the problem.
In that sense, a good survey can very quickly pay for itself.
The Cost of Knowing Is Often Far Less Than the Cost of Finding Out Later
No building survey can guarantee that a property will never develop subsidence or another defect in the future.
What it can do is significantly improve the information available to you before you commit to the purchase. That distinction is important.
Discovering a serious defect after completion means the problem is now yours to manage, fund and insure.
Discovering it before exchange means you still have options;
- You can seek further advice.
- You can obtain quotations.
- You can negotiate.
And, where necessary, you can decide that the property is not the right purchase for you.
Buying a Property? Get It Surveyed Before You Commit
Whether you require a Level 2 HomeBuyer Report or a more comprehensive Level 3 Full Building Survey, the objective is the same: to make sure you properly understand what you are buying before you become responsible for it.
With the average subsidence claim now around £20,000, overlooking a significant structural defect can prove considerably more expensive than investigating the property properly before purchase.
At Stokemont, our RICS Surveyors inspect properties across London and the surrounding areas, providing practical and straightforward advice to help purchasers make informed decisions.
Get an instant quote for our Level 2 HomeBuyer Report and Level 3 Full Building Survey now!


